Start with the carrier, not a discount claim
Insurers evaluate properties, policies, loss history, occupancy, construction, operations, safeguards, and many other factors. Some may consider professionally installed security measures; others may not offer a direct credit. Ask for written guidance on recognized systems, monitoring, certifications, maintenance, and evidence requirements.
Improve incident documentation
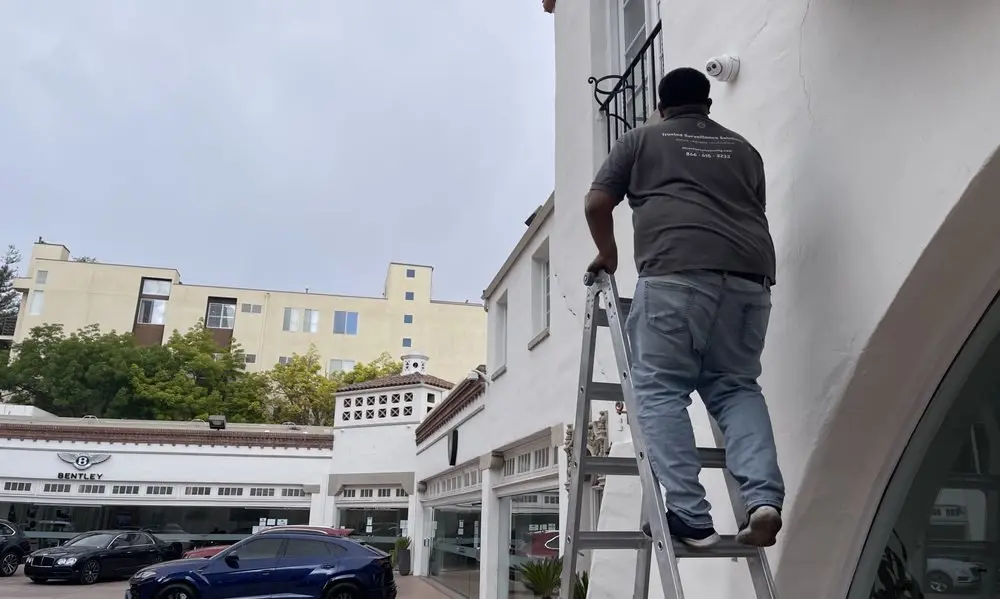
Properly placed cameras may provide timelines, descriptions, vehicle information, activity patterns, and other evidence after theft, vandalism, liability events, or property damage. Image quality, time accuracy, retention, export procedures, and chain of custody affect whether that footage is useful.
Support loss-control recommendations
A professional risk assessment can document vulnerable approaches, loading areas, entrances, cash-handling points, parking, restricted areas, and after-hours conditions. Camera systems may then be coordinated with lighting, alarms, access control, intercoms, gates, monitoring, or operational procedures.
Use monitoring and alerts carefully
Where appropriate, supported video events or alarm signals can be reviewed through a defined monitoring and response workflow. The insurer may distinguish between local recording, self-notification, verified response, and professionally monitored services, so confirm the policy language.
Maintain records over the system lifecycle
Keep the project scope, equipment list, coverage documentation, user permissions, training records, maintenance findings, and material changes organized. Verify recording and time settings regularly so the system remains dependable rather than becoming a control that exists only on paper.
Measure value beyond the premium
Even when no insurance credit applies, cameras may improve awareness, investigation, operational accountability, remote support, and the ability to learn from incidents. Those outcomes should be evaluated alongside equipment, installation, storage, monitoring, and lifecycle costs.